An Abu Dhabi court has ruled that a man must repay a Dh120,000 loan while also providing Dh15,000 in compensation, following a legal dispute over the outstanding debt and the financial losses claimed by the lender.
Abu Dhabi Court Directs Borrower to Repay Dh120,000 and Award Dh15,000 in Damages.
The court found that the borrower’s failure to return the amount had resulted in financial hardship and emotional suffering for the lender. As a result, the judge ordered the borrower to pay an additional Dh15,000 as compensation for the damages caused.
An Abu Dhabi court has ordered a man to repay Dh120,000 that he had borrowed from another individual during what was described as an emergency situation. In addition to returning the full amount, the borrower has also been directed to pay Dh15,000 in compensation to the lender after the dispute over repayment escalated into a legal case.
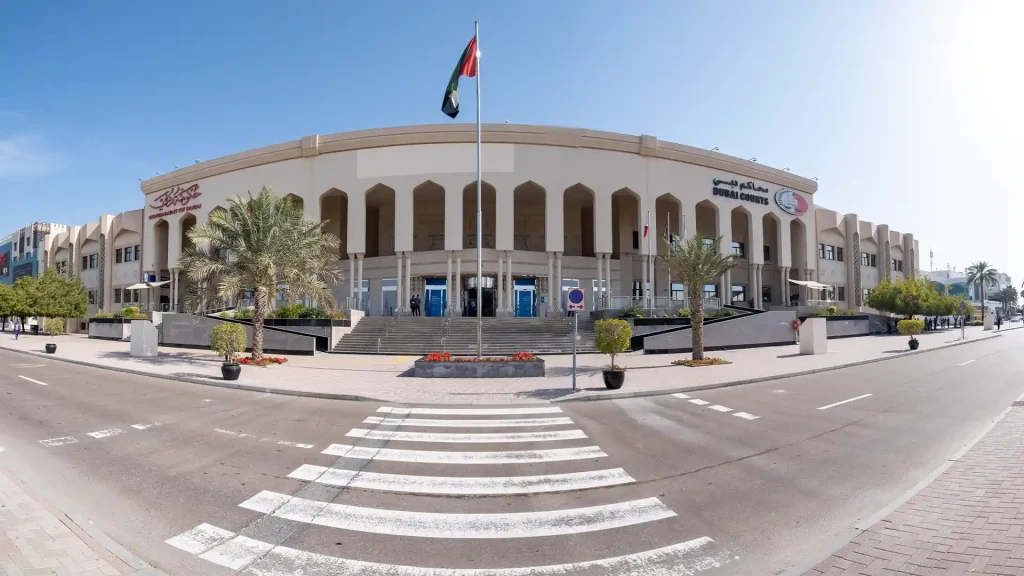
The ruling was issued by the Abu Dhabi Family, Civil and Administrative Claims Court following a complaint filed by the lender, who claimed that the money had been provided to the defendant as a loan and was expected to be returned. According to the case records, the lender had agreed to assist the man financially when he was facing an urgent situation.
The financial assistance was provided in two separate transfers. The first payment amounted to Dh20,000, while a second transfer of Dh100,000 was made later. Together, the two transactions brought the total amount advanced to Dh120,000.
The lender later sought the return of the money, arguing that the amount had been given as a loan rather than as a gift or permanent financial assistance. However, according to the details presented before the court, repeated attempts to recover the money did not result in repayment. The lender alleged that the borrower eventually stopped responding to requests and failed to settle the outstanding amount.
With the repayment issue unresolved, the lender decided to take the matter to court and sought legal intervention to recover the money. The claim was based on the assertion that the borrower had received the funds and was obligated to return them.
During the proceedings, the court examined the circumstances surrounding the transfers and the claims made by both parties. The financial transactions were significant to the case because they established that the lender had actually transferred the stated amounts to the borrower. The two payments, Dh20,000 and Dh100,000, together demonstrated that Dh120,000 had been provided.
The court ultimately found that the borrower was responsible for returning the money. It ordered him to repay the entire Dh120,000 to the lender. The decision also included an additional Dh15,000 compensation award.
The compensation was separate from the original loan amount. While the Dh120,000 represented the money that the borrower was required to return, the additional Dh15,000 was ordered in recognition of the difficulties and distress the lender was said to have experienced during the dispute.
The case highlights the importance of clearly documenting financial arrangements, particularly when substantial sums of money are transferred between individuals. Even when money is provided to help someone during an emergency, disagreements can arise later if the terms of repayment are not clearly established.
In this case, the lender maintained that the money was provided with the expectation that it would eventually be returned. After the borrower allegedly failed to respond to repayment requests, the dispute moved beyond a private disagreement and became the subject of formal court proceedings.
The court’s ruling means that the borrower is now legally required to satisfy both parts of the judgment. He must return the original Dh120,000 and pay the additional Dh15,000 awarded as compensation, bringing the total financial liability under the judgment to Dh135,000.
The sequence of events began with the lender’s decision to provide financial support when the borrower reportedly needed urgent assistance. The first transfer of Dh20,000 was followed by a much larger payment of Dh100,000. Although the combined amount was substantial, the lender said the money was provided as a loan.
Problems reportedly emerged when the time came to recover the funds. Instead of receiving repayment, the lender alleged that the borrower became unresponsive to repeated requests. The continued lack of repayment eventually prompted the lender to seek a judicial remedy.
The court’s decision provides a resolution to the financial dispute by formally recognising the borrower’s obligation to repay the amount received. It also demonstrates that a dispute involving a personal loan can result in additional financial consequences when the lender suffers hardship or distress as a result of the failure to repay.
For people who lend money to friends, relatives, acquaintances or other individuals, the case serves as a reminder of the value of keeping clear records. Written agreements, transfer records, receipts and messages discussing the purpose of a payment can help establish whether money was intended as a loan or as a gift.
Financial disputes can become particularly complicated when large amounts are transferred without a clearly documented repayment schedule. Although personal relationships may encourage people to provide assistance quickly during emergencies, documenting the arrangement can help both sides avoid misunderstandings later.
The Abu Dhabi case also illustrates how a private financial disagreement can eventually reach the courts when the parties are unable to resolve the matter themselves. Once a legal claim is filed, transaction records and other evidence can become important in determining whether an obligation exists and what amount is owed.
In the present case, the documented transfers played an important role in establishing the amount at issue. The lender had transferred Dh20,000 in one payment and Dh100,000 in another, making the total Dh120,000. The court subsequently ordered the borrower to return that entire sum.
The additional Dh15,000 compensation means the court’s final financial order goes beyond simply restoring the lender’s original funds. The compensation reflects the court’s decision concerning the consequences of the dispute and the difficulties allegedly experienced by the lender while attempting to recover the money.
The judgment brings the dispute to a formal conclusion, requiring the borrower to meet the financial obligations imposed by the court. The case is a reminder that emergency financial assistance can create significant legal obligations when the money is provided as a loan.
For lenders, the situation underlines the importance of communicating repayment terms clearly before transferring substantial sums. For borrowers, it highlights the need to honour agreed financial commitments and maintain communication with lenders if repayment becomes difficult.
Ultimately, the Abu Dhabi court ruled in favour of the lender’s claim for repayment. The borrower was ordered to return the Dh120,000 he had received through the two transfers and to provide a further Dh15,000 in compensation. The decision underscores the legal consequences that can follow when a personal loan remains unpaid and attempts to resolve the matter privately fail.
Borrower sought financial help during emergency
A personal loan dispute in Abu Dhabi has ended with a court ordering a man to return Dh120,000 that he had received from another individual after reportedly seeking financial assistance during an unexpected emergency.
The case came before the Abu Dhabi Family, Civil and Administrative Claims Court after the lender said the borrower had failed to honour his commitment to repay the money. According to the lender’s account, the financial assistance was provided after the borrower approached him during a difficult situation and explained that he urgently needed funds.
The lender said the money was never intended to be a gift. It was provided on the understanding that the borrower would return the amount once his financial circumstances improved.
The funds were transferred in two instalments. The first transaction involved Dh20,000, while the second payment amounted to Dh100,000. Together, the transfers totalled Dh120,000.
At the time the money was provided, the lender said he trusted the borrower’s promise that the amount would eventually be repaid. However, the situation reportedly changed when the lender later attempted to recover the money.
According to the complaint, the borrower initially communicated with the lender about the outstanding amount but subsequently became increasingly difficult to reach. The lender alleged that telephone calls and messages seeking repayment were ignored.
The repeated attempts to obtain the money eventually led the lender to seek legal assistance. He filed a civil claim asking the court to order the borrower to return the full Dh120,000.
In addition to recovering the principal amount, the lender also sought compensation. He argued that he had been deprived of the opportunity to use his money during the period in which it remained with the borrower and that the prolonged dispute had caused him distress.
Financial records presented before the court
To establish his claim, the lender provided documentary evidence relating to the transactions.
Among the material submitted to the court were bank transfer records showing the two payments made to the borrower. The records supported the lender’s assertion that the money had actually been transferred and established the total value of the funds involved.
The lender also produced WhatsApp conversations exchanged between the two parties.
The electronic messages were important to the case because, according to the court records, they contained communications in which the borrower acknowledged receiving the money. The conversations also included assurances from the borrower that the amount would be repaid.
The messages therefore provided additional evidence supporting the lender’s position that the money had been advanced as a loan rather than transferred without any expectation of repayment.
The lender relied on these conversations to demonstrate that the borrower was aware of the outstanding obligation. The communications also showed that repayment had been discussed between the two men.
According to the lender, the nature of the conversations changed over time. While the borrower had initially indicated that he would settle the amount, the lender claimed that he later stopped responding properly to requests for repayment.
The lender said his attempts to communicate through messages and calls were unsuccessful, leaving him with no practical option other than pursuing the matter through the courts.
Borrower accepts receiving the money
During the proceedings, the borrower did not dispute one of the central facts of the case: he had received the Dh120,000.
He acknowledged before the court that the money had been transferred to him. He also confirmed that he had requested the financial assistance because he was dealing with an emergency.
The borrower maintained that he had intended to repay the money. He therefore did not portray the transaction as a gift or deny that an obligation to return the funds existed.
However, he challenged part of the lender’s claim.
The borrower argued that the two parties had never established a definite date by which the entire amount had to be repaid. In his view, there was no agreed deadline that could be used to establish that he had deliberately failed to honour a specific repayment schedule.
He also rejected the suggestion that he had intentionally refused to repay the money.
According to his defence, the reason for the delay was his continuing financial difficulties. He said additional financial problems had affected his ability to settle the outstanding amount.
The borrower therefore asked the court to distinguish between an inability to pay immediately and an intentional refusal to repay.
He accepted responsibility for the original Dh120,000 but opposed the additional compensation being sought by the lender.
His position was that the court should not impose an amount beyond the principal debt. He requested that any claim for compensation be dismissed and that his financial liability be limited to the Dh120,000 he had originally received.
Dispute centred on repayment and compensation
The court therefore had to consider two main issues.
The first was whether the Dh120,000 represented a genuine debt that remained outstanding.
The second concerned the lender’s request for additional compensation arising from the delay in recovering the money.
The evidence presented during the case included the bank records showing the transfers, the WhatsApp exchanges between the parties and the borrower’s own admission that he had received the funds.
Taken together, the evidence established a clear financial relationship between the two men.
The transfer receipts demonstrated that the lender had provided the money. The electronic communications showed discussions about repayment, while the borrower’s admission confirmed that he had received the full amount.
The court consequently found that there was sufficient evidence to establish the existence of the debt.
The absence of a precise repayment date did not, in the court’s assessment, eliminate the borrower’s obligation to return money that had been received as a loan.
The borrower had acknowledged the funds and had not disputed the underlying transaction. His explanation that he had experienced further financial difficulties was considered in the context of his obligation to repay the money.
Court confirms obligation to return the debt
After reviewing the evidence, the court ruled that the borrower remained responsible for returning the Dh120,000.
The judges relied on the combination of the bank documentation, the messages exchanged through WhatsApp and the borrower’s admission in court.
The evidence established that the money had been transferred to the borrower and that it had not subsequently been returned to the lender.
The court applied the basic legal principle that a person who possesses another individual’s money without a valid legal basis cannot simply retain it indefinitely.
Where funds have been received under an obligation to return them, the recipient remains responsible for restoring the money to its rightful owner.
The court therefore rejected the borrower’s attempt to limit the dispute to an issue of repayment timing.
Although the borrower said he had faced additional financial difficulties and had not deliberately refused to pay, those circumstances did not remove his responsibility for the debt.
The court concluded that the lender was entitled to recover the money that had been provided.
Compensation considered separately
The court also considered the lender’s request for compensation.
The lender had argued that keeping the money from him had prevented him from using his own funds for the period during which the borrower failed to return them.
The dispute had also allegedly caused the lender emotional strain. Instead of resolving the matter privately, he had been required to repeatedly request repayment and eventually bring the issue before the court.
The judges recognised that the continued withholding of the funds had deprived the lender of their use.
The court consequently determined that the lender had suffered consequences beyond the simple fact that the principal amount remained unpaid.
The financial impact of being unable to access one’s own money can be significant, particularly when the lender has to spend time and effort attempting to recover it.
In this case, the court took into account the circumstances surrounding the non-payment and the distress described by the lender.
The ruling therefore went beyond ordering repayment of the original amount.
Evidence from digital communications
The case also demonstrates the potential importance of digital communications in financial disputes.
The WhatsApp messages submitted by the lender were not merely presented as evidence that the two men had communicated. They were used to support the claim concerning the nature of the transaction and the borrower’s awareness of the obligation to repay.
In modern personal lending arrangements, conversations through messaging applications can contain important details about why money was transferred, whether it was intended as a loan, and whether the recipient later acknowledged the debt.
Here, the messages reportedly contained acknowledgements from the borrower and assurances that repayment would take place.
This evidence complemented the bank records.
A bank statement can establish that money moved from one account to another, but it may not always explain why the transfer occurred. Communications between the parties can provide context about the purpose of a transaction.
In this dispute, the two forms of evidence worked together. The financial records established the transfers, while the messages helped demonstrate the understanding between the parties regarding repayment.
The borrower’s admission during the court proceedings further strengthened the lender’s case.
Borrower’s financial difficulties did not cancel debt
The borrower argued that his inability to repay was connected to further financial problems.
Financial hardship can make repayment difficult, but the court’s ruling made clear that such circumstances did not automatically erase an established obligation.
The borrower had acknowledged receiving the money and had accepted that the funds had been borrowed during an emergency.
His disagreement concerned the timing of repayment and the additional compensation claimed by the lender.
The court nevertheless found that the underlying debt remained due.
The ruling reinforces the distinction between a person’s ability to pay immediately and the existence of an obligation to repay. A borrower may experience genuine financial difficulties, but those difficulties do not necessarily transform a loan into a gift.
A reminder about personal loans
The case provides a broader reminder about the risks associated with informal lending arrangements.
People frequently provide financial assistance to friends, relatives, colleagues or acquaintances when someone encounters an unexpected problem. Such arrangements can sometimes be based largely on trust, with repayment terms discussed verbally or through casual messages.
Problems may arise when the borrower later experiences financial difficulties or when the parties have different understandings about when repayment should occur.
Keeping written records can help prevent such disagreements.
A clear written agreement can identify the amount borrowed, the purpose of the transaction, the expected repayment date and any other relevant conditions. Bank transfer records can also provide an objective record of the money changing hands.
Similarly, messages between the parties can become important if a disagreement develops.
The Abu Dhabi case illustrates how several pieces of evidence can collectively establish the existence of a financial obligation.
Court brings dispute to conclusion
The proceedings ultimately resolved the disagreement in favour of the lender’s claim for repayment.
The court determined that the borrower had received Dh120,000 and that the amount remained unpaid. The lender’s bank records, WhatsApp conversations and the borrower’s own admission provided sufficient evidence to establish the debt.
The court also concluded that retaining the lender’s money had deprived him of its use and contributed to the difficulties and distress associated with the dispute.
As a result, the borrower was required to return the Dh120,000 and was also ordered to pay compensation.
The decision serves as a reminder that personal financial arrangements can have legal consequences even when they begin as an act of emergency assistance between two individuals.
What may initially appear to be a simple request for help can become a formal legal dispute if repayment does not take place and communication breaks down.
For lenders, the case highlights the importance of preserving transaction records and written communications. For borrowers, it demonstrates that acknowledging a loan and promising repayment can carry significant consequences if the debt remains outstanding.
Ultimately, the Abu Dhabi court found that the evidence clearly established the existence of the debt. The borrower’s admission that he had received the money, together with the bank transfer documents and digital conversations, supported the lender’s case.
The court consequently held that the borrower could not retain the funds indefinitely. Having received the money under an obligation to repay it, he remained responsible for returning the amount.
The additional compensation recognised the impact of the prolonged withholding of the funds on the lender. The case therefore ended not only with an order to restore the original Dh120,000, but also with a financial award addressing the consequences of the dispute.
The ruling demonstrates the importance of fulfilling financial commitments and maintaining clear records whenever substantial sums are lent between individuals. It also shows that when informal attempts to recover a debt fail, documentary and digital evidence can become critical in establishing what happened before a court.